TECHNICAL GUIDE / 2026-10-03
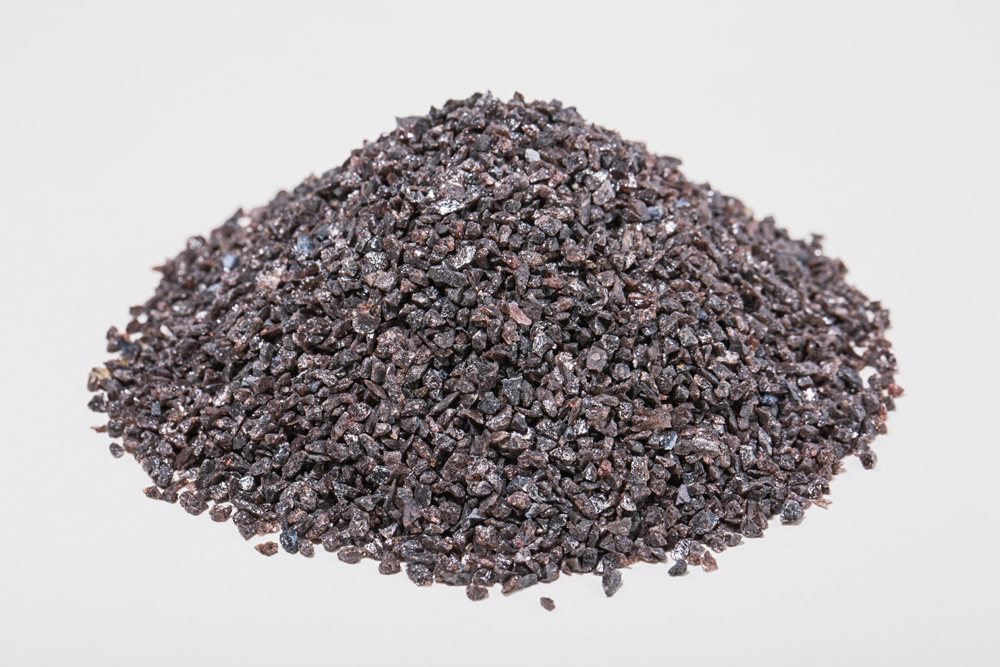
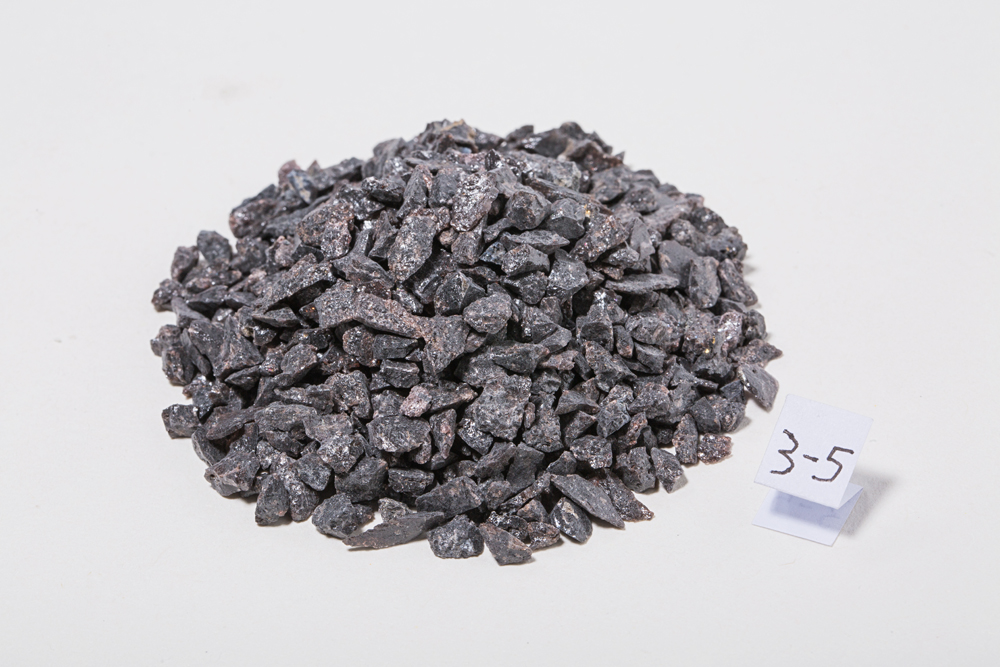
China's week-long National Day holiday (October 1–7) is underway, but brown fused alumina smelters across the country are maintaining production. Tilting furnaces are designed for continuous operation — shutting down and restarting costs more than keeping them running — so holiday production is the industry norm.
Pre-Holiday Data (as of September 18)
Alumina: Domestic spot prices averaged RMB 2,673/ton. National inventory reached 6.776 million tons, up 70,000 tons week-on-week. Of 118.42 million tons of built capacity, 90.78 million tons were operational, putting the operating rate at 76.66% (CIF Futures data).
Bauxite: Guinean bauxite was quoted at $72/dry ton. Ocean freight rose $1 to $43/ton, bringing CIF to $74/ton. Guinea's proposed bauxite export control measures remain under study, with no formal policy issued yet.
Supply Chain Divergence
Raw materials and finished products are moving in different directions. Bauxite prices are holding firm on policy expectations and elevated freight costs, while alumina inventories continue to build on rapid capacity releases. For brown fused alumina producers caught in the middle, cost pass-through to product prices takes time.
What to Watch After the Holiday
- Downstream restart pace — order recovery from abrasives and refractories manufacturers
- Bauxite freight trends — whether the $43/ton rate comes down
- Alumina inventory — October–November import arrivals will directly affect the stockpiling pace
The industry returns to normal production rhythm after the 7-day break. The data will tell the story from here.